
Cash without tax returns · No hard credit pull · No call center
No tax returns required. Your equity in 5 days.
Carrying high-interest credit card debt? Put your home equity to work and consolidate it in one closing. Self-employed, with write-offs that hide your real income? One CPA-prepared P&L replaces your tax returns. Either way — see your options in 60 seconds, no hard credit pull.
- 5-Day HELOC — tap up to 90% of your home’s value, no appraisal, funded in as little as 5 days. see how it works →
- No Income Verification HELOC — no tax returns, W-2s, or pay stubs at 680+ credit on lines of $150K or more. see how it works →
- P&L Only — one CPA-prepared P&L is your whole income file. No tax returns, no bank statements. P&L loan guide →
- Primary or investment property — your deal lands on Anthony’s desk, not a call center’s.
- No hard credit pull to see your options — and your info is never sold.
Or skip the form — call or text 949-868-2422
- 5.0 verified client reviews
- NMLS #1996696
- Irvine, CA · 100+ lender network
60 seconds · no hard credit pull · never sold
What loan type are you interested in?
You’ll work directly with Anthony HuynhVice President · NMLS #1996696
- HELOC APR from*
- 6.75%
- HELOC up to CLTV
- 90%
- HELOC funded in as little as
- 5 days
- P&L Only loan
- No tax returns
- Lender network
- 100+
Why 5 days is possible: no appraisal (automated valuation) → soft credit pull → e-sign → fund. Days, not weeks.
*HELOC APR starts at 6.75% for the most qualified borrowers. It is a variable rate tied to an index that can change; your actual APR depends on credit profile, CLTV, property type, occupancy, and line amount. A maximum APR applies and is disclosed at account opening, and plan fees may apply. Program terms depend on credit profile, LTV, property type, occupancy, and loan specifics, and are subject to change. Nothing here is a commitment to lend or an offer of specific loan terms. All loans subject to credit approval.
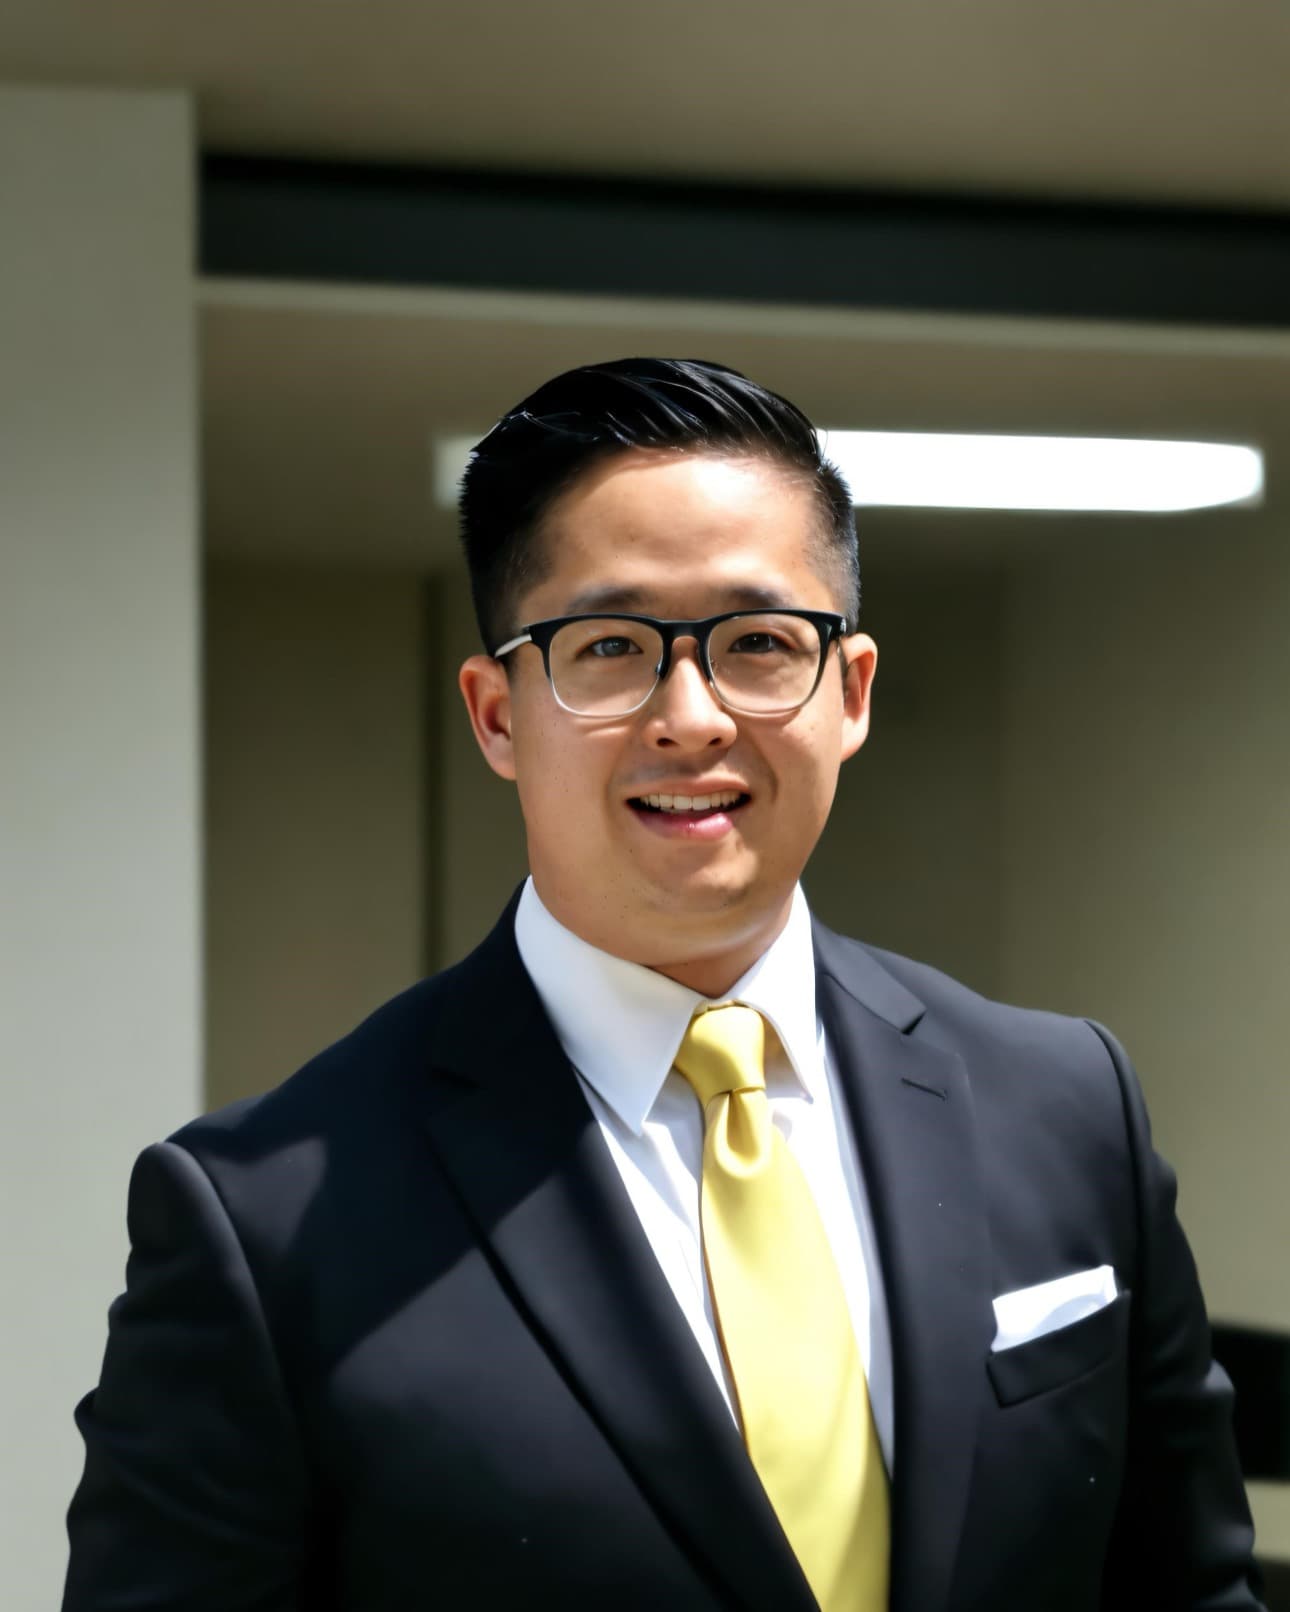
Anthony Huynh
Vice President · Elevate Mortgage
Your loan officer
Work directly with Anthony.
Licensed in 30 states, I help homeowners and real estate investors secure financing that actually fits, from HELOCs, conventional loans, and government programs to investor products like DSCR and hard money.
- 5.0 verified client reviews
- NMLS #1996696
- Irvine, CA · 100+ lender network
Know Before You Apply
Can we fund your deal? Check before you apply.
Better to know now than after an application. Here’s what we can and can’t do, plainly stated.
Show me what you can and can’t fund
We can help with:
- HELOCs from $50K to $5M, up to 90% combined LTV (Texas 80%), 620+ credit — primary homes and investment properties in 30 states
- DSCR rental loans at any credit score — below 620 caps at 50% LTV; $75K–$3M in 44 states plus Washington, D.C.
- P&L Only loans at 640+ credit from $150,000 — no tax returns, no bank statements
- Bank statement loans at 620+ credit, qualified on 12–24 months of deposits
- Home Equity Agreements — credit accepted from the 500s, up to $600,000, no monthly payments (AZ, CA, CO, FL, OH, OR, PA, TN, UT, VA and WA)
- Reverse mortgages — no minimum credit score, age 62+, primary residence
- Hard money — investment properties in 44 states plus Washington, D.C.; primary residences in CA, ID, OR and WA only
- Conventional, FHA & VA — including below-620 conventional exception paths, FHA credit considered from 500, and VA cash-out up to 100% LTV (VA cash-out not available in Texas)
We’re not the right fit for:
- Any property in IL, MA and NY — we can’t lend there today
- A home you live in outside Anthony’s 30 states of licensing — see where we lend
- HELOCs under 620 credit or under $50,000
- P&L Only loans under 640 credit or under $150,000
- Second homes on a bank statement loan
If your situation changes, come back — we’d genuinely like to take another look. Gray-area scenario? Call or text 949-868-2422.
Credit below 620? See the HEA credit tiers (500s OK)
| FICO score | Max. OLTV |
|---|---|
| 500 – 539 | 60% |
| 540 – 579 | 65% |
| 580+ | 75% |
On a Home Equity Agreement your FICO band sets the maximum OLTV (investment properties run 10 points lower) — up to $600,000, with no monthly payments. See the full HEA program →
Loan Programs
12 programs. One conversation.
From 5-day HELOCs to DSCR rentals and VA cash-out — every program priced across a 100+ lender network, with the trade-offs explained in plain English.
- ★ Most Popular
5-Day HELOC
Tap equity without touching your first mortgage — up to 90% CLTV, no appraisal.
See options → - ★ Self-Employed
P&L Only Loan
One P&L statement is your whole income file — no tax returns, no bank statements.
See options → - ★ Investors
DSCR Loan
Long-term, short-term and 2–4 unit rentals — the property’s rent does the qualifying.
See options → - Self-Employed
Bank Statement Loan
Qualify with 12–24 months of personal or business deposits instead of tax returns.
See options → - Cash In Hand
Cash-Out / Investor Refinance
Replace your mortgage and take a lump sum, or reposition rental debt.
See options → - Buy & Hold
Rental Property Loan
Financing for rentals and 2–4 unit multi-family, qualified on the rent.
See options → - Speed
Hard Money
Fast, asset-based funding for deals that can’t wait for a bank.
See options → - Classic
Conventional Loan
The classic home loan for purchases and refinances, with removable PMI.
See options → - Flexible Credit
FHA Loan
Government-backed financing for owner-occupied 1–4 unit homes.
See options → - Veterans
VA Loan
Cash-out up to 100% LTV and no monthly mortgage insurance for those who served.
See options → - 62+
Reverse Mortgage
Turn equity into cash with no monthly mortgage payment.
See options → - Credit From the 500s
Home Equity Agreement
Equity cash today with no monthly payments — credit accepted from the 500s.
See options → - Not Sure?Let the funnel decide.Answer a few quick questions and we’ll route your scenario to the right program — 60 seconds, no hard credit pull.Find my program →
Recently Funded
Recently funded deals.
A sample of loans funded for clients across the country — borrower details omitted for privacy.
- HELOC
Ladera Ranch, CA · Funded Aug 2026
$500,000
- HELOC
Phoenixville, PA · Funded Aug 2026
$495,000
- Hard Money
San Pedro, CA
$433,000
- HELOC
Levering, MI · Funded Aug 2026
$392,000
- Non-QM Cash-Out Refi
Tampa, FL · Funded Aug 2026
$346,500
- DSCR
Denver, CO
$200,000
| Program | Location | Loan amount | Funded |
|---|---|---|---|
| HELOC | Ladera Ranch, CA | $500,000 | Aug 2026 |
| HELOC | Phoenixville, PA | $495,000 | Aug 2026 |
| Hard Money | San Pedro, CA | $433,000 | — |
| HELOC | Levering, MI | $392,000 | Aug 2026 |
| Non-QM Cash-Out Refi | Tampa, FL | $346,500 | Aug 2026 |
| DSCR | Denver, CO | $200,000 | — |
Examples of actual funded transactions; borrower details omitted for privacy. Past transactions are not a guarantee of loan approval or terms. All loans subject to credit approval.
5 out of 5 stars
“Anthony was extremely helpful and responsive. He quickly found out what we needed and made it happen. Excellent service!”
Jesse W · Pullman, WA · Aug 2026Verified client review 5 out of 5 stars
“The process from start to finish was seamless. Though I had all the required documentation and qualifications, but Anthony was always communicating next steps.”
Charles A · Philadelphia, PA · Aug 2026Verified client review 5 out of 5 stars
“Immediate assist with loan process, willing to help to close out the deal ASAP”
Cuong L · Philadelphia, PA · May 2026Verified client review
Our Process
Go beyond with Elevate Mortgage.
Submit Your Deal
Share your scenario in the 60-second funnel — or one phone call — and we’ll assess your needs.
Customized Solutions
Get tailored loan options designed for your goals, from 100+ lenders.
Application & Approval
Complete your full application and receive fast approvals.
Closing & Beyond
Seamlessly close your loan — in as little as 7-14 days — and enjoy continued support.
Questions, Answered
Straight answers to common questions.
Will checking my options hurt my credit?
No. Seeing your options involves a soft credit review only — no hard pull. A hard inquiry happens later, with your permission, only if you move forward with an application.
How fast can I get a HELOC?
Funded in as little as 5 business days. There is no appraisal (an automated valuation is used), no reserves, and approvals are handled digitally — which is what removes the weeks most people expect from a home equity loan. Texas files take a 12-day minimum under state law. Your actual timeline depends on how quickly your file comes together and is not a guarantee.
Does a HELOC replace my current mortgage?
No. A HELOC sits behind your existing first mortgage as a second lien, so the loan you already have stays exactly as it is. That makes a HELOC a popular way to access equity without refinancing your first mortgage.
Do you need my tax returns or bank statements at all?
No. That’s the whole point of the program — no tax returns, no bank statements, and no deposit-by-deposit reviews of your accounts. Your write-offs stay your business.
Who are P&L Only loans best for?
Business owners, 1099 earners, and self-employed borrowers whose tax returns don’t show their real income — and even W-2 borrowers in the right scenario. If real income and solid credit are there but the paperwork math isn’t, this program is built for you.
What is a DSCR loan?
A DSCR (Debt Service Coverage Ratio) loan qualifies you based on the property’s rental income rather than your personal income. DSCR = gross rental income ÷ total monthly payment (principal, interest, taxes, insurance, and HOA). No W-2s or tax returns are required.
Should I do a cash-out refinance or a HELOC?
It depends on your current first mortgage and how much you need. A cash-out refi replaces your whole loan; a HELOC sits behind it and leaves it untouched. We price both and show you the trade-offs straight — if the HELOC beats the refi for your file, we’ll say so.
Can I qualify with low credit?
Often, yes. HEA qualification is driven by your equity and your credit band rather than a hard loan-style minimum — many homeowners use an HEA to access equity while rebuilding credit, then refinance out later at a score no bank would have offered them when they started.
Ready to fund your next deal?
Whether it’s equity, a rental, or a purchase — see your options in 60 seconds with no hard credit pull, or talk it through with Anthony.
Prefer a set time? Book a call · Ready to apply? Start your full application
West Capital Lending, Inc. is an Equal Housing Lender. We do not discriminate on the basis of race, color, religion, national origin, sex, handicap, or familial status.